Collective agreements regulate pay, working hours, and other employment conditions for a significant share of Germany’s workforce. Data from the German Federal Statistical Office (Destatis) shows that around 49% of employees in Germany worked under either an industry-level or company-level collective agreement in 2024. For workers covered by structured agreements, knowing how earnings are determined can make future income easier to estimate.
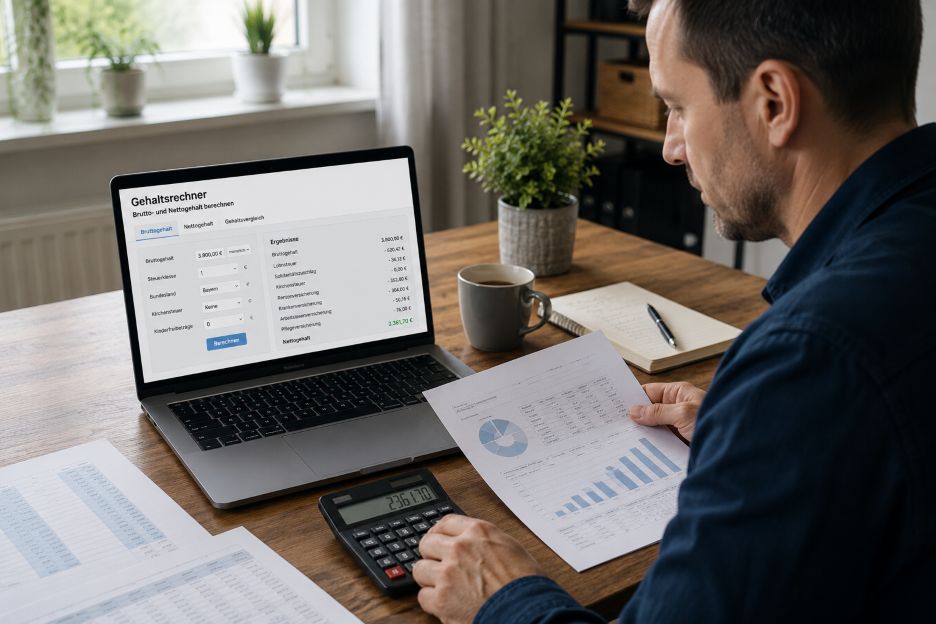
That visibility can be useful when creating a household budget or planning several years ahead. A worker who knows their current salary grade and upcoming negotiated increases can use a salary calculator (translates to gehaltsrechner in German) to estimate earnings and compare future income with expected expenses. The result is still a forecast rather than a guarantee, but it provides a firmer starting point than planning without a clearly defined pay structure.
Why Predictable Income Matters for Financial Planning
Long-term financial decisions depend heavily on cash flow. Buying a home, reducing debt, investing regularly, and preparing for retirement all require households to judge how much income may remain after essential expenses.
Predictability does not mean that every future expense can be known. Inflation, taxes, interest rates, family circumstances, and unexpected costs can all change. What a structured salary system does provide is greater clarity on one side of the household equation: employment income.
The German Federal Statistical Office tracks collectively agreed monthly and hourly earnings through its official earnings statistics. Such data illustrates how negotiated wage arrangements create measurable changes in employee compensation rather than leaving every adjustment to individual negotiations.
How IG Metall’s Pay Structure Provides Greater Visibility
IG Metall publishes pay tables covering monthly earnings, apprenticeship compensation, allowances, holiday provisions, and other employment conditions across industries and regions. Within the metal and electrical industry, its Entgeltrahmenabkommen, commonly known as ERA, provides a structured method for assigning employees to pay groups.
The union explains that ERA replaced the former separation between wage groups for manual workers and salary groups for employees. Jobs are instead evaluated using common rules. The relevant work assignment, responsibilities, knowledge, and other job characteristics help determine the appropriate compensation group.
This matters financially because workers can understand where their current earnings come from. They may also have a clearer picture of what changes in duties or classification could mean for future pay. It does not remove uncertainty surrounding career progression, but it makes the underlying compensation system more transparent.
Scheduled Increases Turn Future Income Into Something More Measurable
Negotiated increases can add another layer of predictability. IG Metall reports that employees in collectively covered metal and electrical companies received a nationwide 2% pay increase from April 2025, followed by another 3.1% from April 2026 under the agreement reached in November 2024.
Knowing the timing and size of an agreed increase allows a household to estimate how much additional gross income may become available. Instead of treating a future raise as unexpected spending money, workers can assign some of it to existing financial priorities before it reaches their bank account.
Planning for a Home Purchase
A home purchase usually requires years of preparation. Future income estimates can help households set savings targets for a deposit and related purchasing costs. They can also compare projected housing expenses with expected earnings rather than relying entirely on today’s salary.
Interest rates remain an important variable. The European Central Bank explains that changes in monetary policy influence borrowing conditions across the euro area, which means mortgage costs can shift even when a worker’s salary progression is relatively predictable. A pay schedule therefore provides useful information, but it should be considered alongside changing financing costs.
Paying Down Debt With Future Raises
Scheduled wage progression can also support debt planning. Someone expecting an agreed increase could decide in advance that part of the additional net income will go toward outstanding balances.
This approach can reduce the temptation to expand regular spending as soon as earnings rise. The important calculation is based on net income after taxes and social contributions, rather than simply applying the headline percentage increase to the household budget.
What Changes When Investing Becomes a Regular Expense?
Predictable earnings can make regular investing easier to incorporate into monthly finances. Instead of investing whatever happens to remain at the end of the month, workers can treat contributions as a planned expense and adjust them when income changes.
The Deutsche Bundesbank regularly examines household wealth and financial behavior through its Panel on Household Finances. Its research highlights the wide range of assets and liabilities held by German households, reinforcing why investment decisions should be viewed as part of a broader financial position rather than in isolation.
A scheduled raise could therefore be divided among several priorities. One portion might strengthen cash reserves, another could reduce debt, and a further amount could increase long-term investments. For workers who are still learning how to balance these priorities, understanding smart financial management for beginners can provide useful context for connecting everyday budgeting decisions with longer-term investment goals. The right balance ultimately depends on the household’s circumstances, financial priorities, and tolerance for risk.
Retirement Planning Benefits From a Longer View
Retirement is perhaps the clearest example of why income visibility matters. Preparing for life after work requires assumptions about earnings, savings rates, investment returns, inflation, and future expenses over many years.
Clearly defined salary structures cannot answer all those questions. They can, however, give workers a more reliable income baseline for building projections. Regular reviews can then account for negotiated wage changes, promotions, career moves, or periods of reduced working hours.
Predictability Helps, but Plans Still Need Flexibility
A salary table should never be treated as a promise that a household’s finances will follow a perfectly straight path. Collective agreements are renegotiated, job classifications can change, and personal circumstances may shift unexpectedly. Taxes, inflation, borrowing costs, and investment performance introduce additional uncertainty.
The advantage of a transparent pay structure is therefore practical rather than absolute. Systems such as the ERA framework used in parts of IG Metall‘s bargaining area give employees clearer information about current compensation and negotiated changes. That information can support better forecasts for savings, debt repayment, investments, and retirement.
Financial planning becomes easier when workers can see further ahead. A predictable salary structure provides a useful foundation, while regular budget reviews keep the plan connected to real life. Used together, those habits can turn future wage progression into progress toward longer-term financial goals.